TCS on Foreign Remittances: Rates, Thresholds and Credits
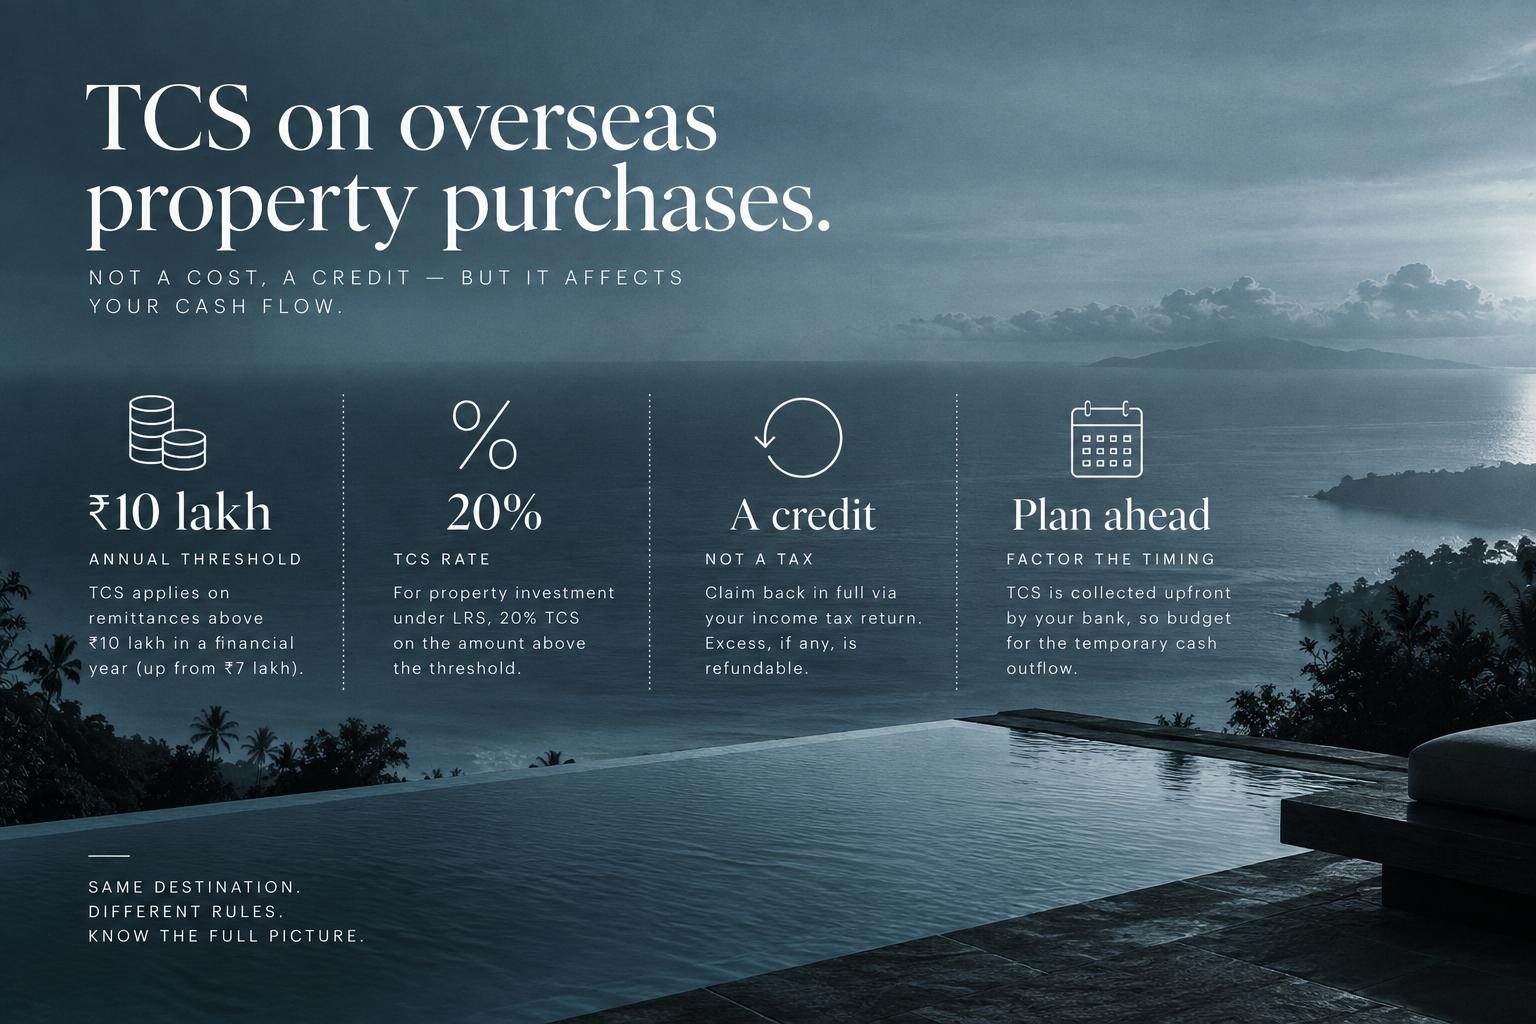
A resident Indian sending money abroad to buy an overseas property assumes, reasonably enough, that TCS is a tax. It is not, and treating it as one is the single most common source of confusion around this rule: TCS is a tax collected at source that the remitter can claim back in full as a credit against their actual income tax liability. The money is not lost, but it is genuinely tied up for a period, and that cash flow reality is worth planning for even though no permanent tax cost is involved.
The threshold and the rate that actually apply
Under the Liberalised Remittance Scheme, an Indian resident can remit up to USD 250,000 per financial year for permitted purposes, which includes overseas property investment. TCS applies on remittances exceeding 10 lakh rupees in aggregate over the financial year, a threshold that was raised from 7 lakh rupees in a recent budget. Remittances for an investment purpose such as buying property attract TCS at 20 percent on the amount above that 10 lakh rupee threshold, a materially higher rate than the reduced rates now applying to education or medical remittances specifically, since property investment is treated differently under the same LRS framework.
Why TCS is a credit, not a cost, and why that distinction still matters
The amount collected as TCS is reflected in the remitter's Form 26AS and can be claimed as a credit against total income tax liability when filing the annual return, in the same way TDS deducted from a salary is credited against final tax due. Where the TCS collected exceeds the actual tax liability for the year, the excess is refundable. This means the true cost of TCS is not the 20 percent itself, it is the opportunity cost of that money being locked up with the tax department from the date of remittance until the credit or refund actually comes through at return filing and processing, which can run to several months.
What this means for timing a large remittance
A buyer remitting a large sum for a property purchase should factor the temporary TCS outflow into their cash flow planning for the transaction itself, since the amount available to actually complete the purchase is reduced by the TCS collected at the point of remittance, not just at tax time. A buyer who remits the full property price without setting aside additional funds to cover the TCS collection may find themselves short of the amount actually needed to close the purchase, a planning gap that is entirely avoidable by budgeting for TCS as an upfront cash requirement even though it is not a final cost.
How the annual threshold resets, and what that means for phased payments
The 10 lakh rupee threshold applies per financial year, not per transaction, which means multiple remittances across the same financial year for staged payments on a single property purchase, common with an off-plan or instalment-based purchase, are aggregated together for TCS purposes. A buyer planning a phased payment schedule that happens to straddle a financial year boundary can, in some cases, structure the timing of remittances to make more efficient use of the annual threshold on each side of the boundary, though this should be planned with a tax adviser rather than assumed to work in every case.
Which bank or authorised dealer actually collects it
TCS is collected by the authorised dealer, typically the remitting bank, at the point the remittance is processed, not by any tax authority directly, and the bank issues a certificate confirming the amount collected that the remitter needs for claiming the credit at return filing time. A buyer working with multiple banks or authorised dealers for different portions of a large remittance should keep each certificate carefully, since the credit claim depends on this documentation matching what the bank has itself reported to the tax department, and a mismatch between the buyer's records and the bank's reporting is exactly the kind of discrepancy that delays a refund considerably.
The gap between TCS and the destination country's own reporting requirements
TCS addresses only the Indian side of a cross-border remittance. Most destination countries carry their own separate reporting requirements once the funds arrive and the property purchase is completed, entirely independent of anything collected at the Indian end. Chanote and Lesser Title Deeds in Thailand and Checking a Certificate at BPN Before You Sign cover destination-side verification steps that sit alongside, not instead of, the TCS compliance covered here, and a buyer who treats TCS as the complete compliance picture for an overseas purchase is missing the destination country's own requirements entirely.
What Avacasa recommends
Budget for the 20 percent TCS as a temporary cash flow requirement on any remittance for property investment above 10 lakh rupees, not as a permanent cost, and file the annual return promptly to claim the credit or refund without unnecessary delay. Where a purchase involves staged payments, plan the remittance schedule with a tax adviser who can account for how the annual threshold interacts with each payment. Inheritance and Succession of Indian Property for NRIs and Declaring Indian Rental Income: ITR and Compliance cover related compliance questions for the reverse direction, money and property moving into rather than out of India.
Before you commit
Can Foreigners Own Property Abroad? Freehold, Leasehold and Use Rights covers the ownership structures this remittance sits on top of, and Due Diligence When Buying Property in Another Country covers the wider verification discipline for any offshore purchase. Australians Buying Abroad: CGT and Foreign Income Reporting and UK, Singapore and Gulf Residents: Reporting and Financing cover the equivalent home-jurisdiction compliance picture for other outbound buyer profiles, worth reading for the parallel each draws with India's own TCS framework. How to Verify a Developer's Track Record and 10 Questions to Ask Before Signing Anything round out the practical checklist regardless of the destination.
Whatever the destination, Thailand, Indonesia and Sri Lanka each carry their own local rules, and the TCS obligation described above applies at the Indian remittance stage before the funds ever reach any of them.
Sources
- The 10 lakh rupee TCS threshold and the 20 percent rate on LRS remittances for investment purposes including property
- TCS as a creditable, refundable collection reflected in Form 26AS rather than a final tax cost
Ready to find your next holiday home?
Browse our curated collection of vacation homes and managed farmland across India and beyond.