Inheritance and Succession of Indian Property for NRIs
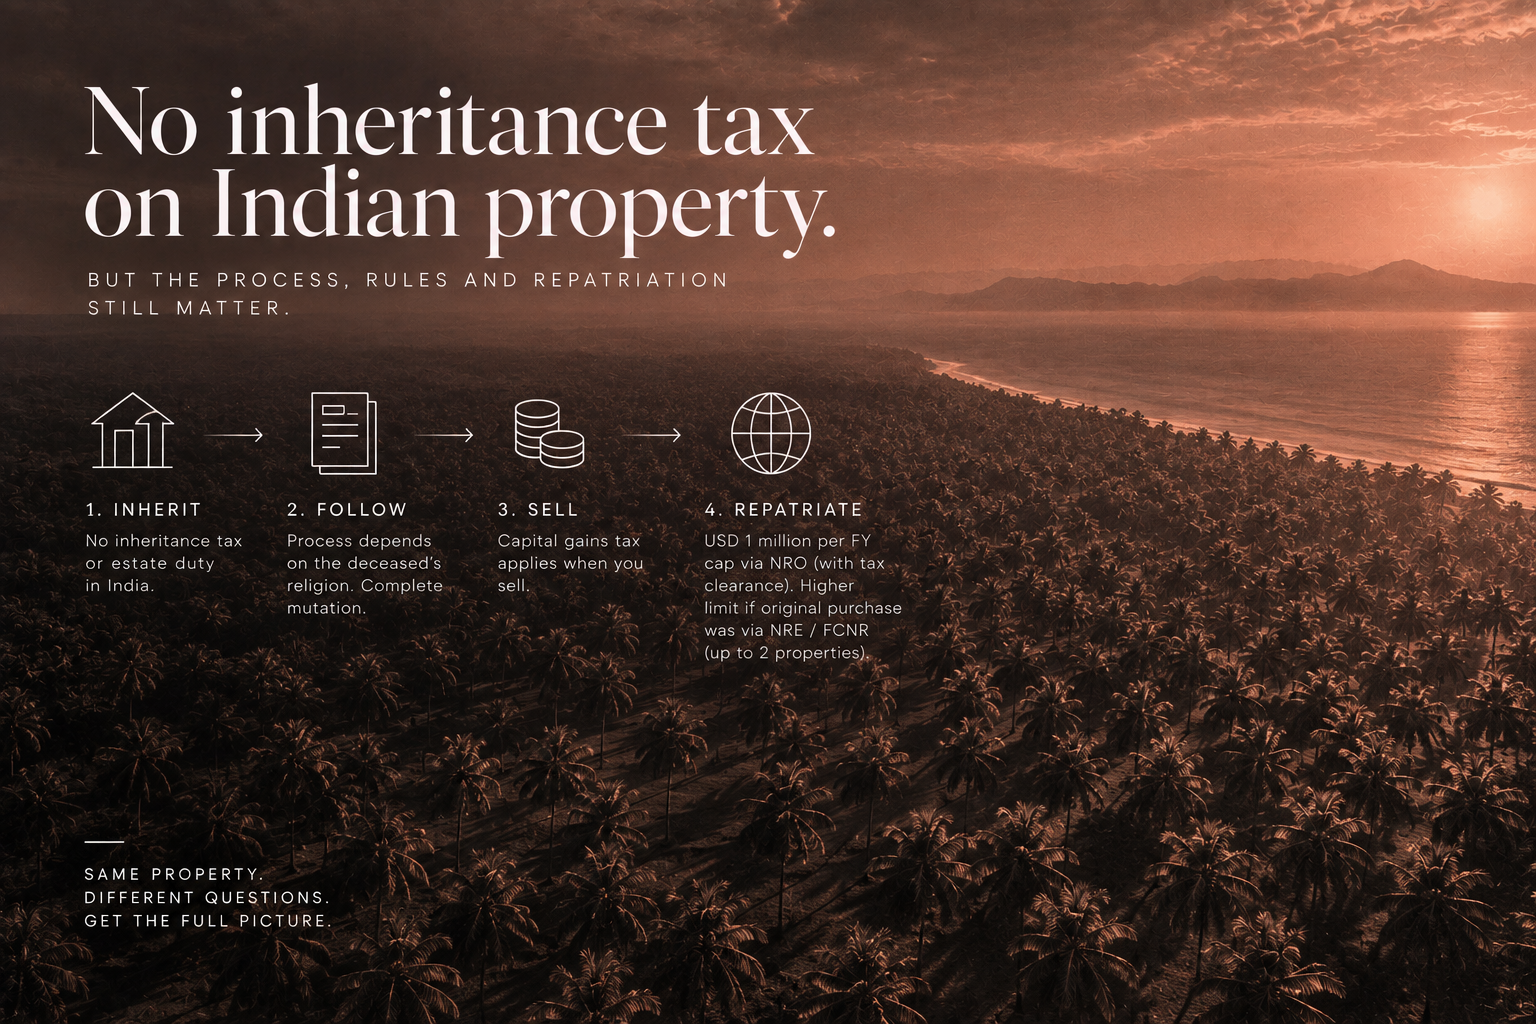
India charges no inheritance tax or estate duty on property passed to an heir, a fact that leads many NRIs to assume inheriting Indian property is administratively simple because it is financially untaxed at the point of transfer. The two things are unrelated. The absence of a tax bill says nothing about which succession law applies, how long the mutation process takes, or what happens to the sale proceeds when an heir living abroad eventually wants the money out of India.
Which law applies depends on the deceased's religion, not on NRI status
India does not run one uniform succession law. The Hindu Succession Act, 1956 governs Hindus, Sikhs, Jains and Buddhists dying without a will, the Indian Succession Act, 1925 governs Christians and Parsis, and Muslim personal law governs Muslims, with meaningfully less freedom to will property away from the shares personal law assigns. An NRI heir's own residency or citizenship status has no bearing on which of these applies. What matters is the deceased's religion at the time of death, and an heir who assumes NRI status somehow simplifies or standardises this is starting from the wrong premise entirely.
Intestate succession, and why a will still matters for an NRI heir
Dying without a will means the applicable personal law's default distribution rules decide who gets what share, which can produce a division among multiple heirs that none of them would have chosen and that is considerably harder to unwind once a property sits in several names, some of them overseas. Where a will exists, the process still requires probate or a succession certificate depending on the state and the nature of the assets, and an NRI heir managing this from abroad faces the added friction of needing a power of attorney or physical presence in India at specific steps, since not every part of the process can be completed remotely.
The actual paperwork trail
The formal process begins with an application to the local tehsildar's office to initiate mutation, the transfer of the property record into the heir's name, supported by a death certificate, a family tree establishing the relationship to the deceased, and identity proof. This mutation step is a revenue-record update, not itself a transfer of legal title, but it is the step most local authorities and banks will require before recognising the heir as the property's owner for any further transaction, including a future sale.
Repatriation is where most NRI heirs actually get surprised
Inheriting the property itself triggers no Indian tax, but selling it later does, and the sale proceeds do not leave India as freely as many NRI heirs assume. Repatriation of sale proceeds through an NRO account is capped at USD 1 million per financial year, and only after applicable capital gains tax has been settled and a chartered accountant has issued the required certification confirming taxes are cleared before the funds can be remitted abroad. Where the deceased originally purchased the property using NRE or FCNR funds, up to two residential properties can have their sale proceeds repatriated without that USD 1 million cap, limited instead to the original foreign exchange amount invested, a distinction worth checking specifically rather than assuming the general cap always applies.
FEMA's separate restriction on agricultural land
An NRI or OCI heir can inherit agricultural land, plantation property or a farmhouse without restriction, since FEMA's purchase restrictions on these categories apply to buying, not to inheriting. The restriction resurfaces at the point of sale: an NRI or OCI cannot sell inherited agricultural land, plantation property or a farmhouse to another NRI or OCI, only to a resident Indian, which meaningfully narrows the buyer pool compared with a residential property carrying no such restriction.
What Avacasa recommends
Confirm which personal law governs the succession before assuming a standard process applies, and complete the mutation formally at the tehsildar's office even where the property is not being sold immediately, since an unmutated record complicates every future transaction. Before relying on the general USD 1 million repatriation cap, check whether the original purchase was funded through NRE or FCNR channels, since that changes the applicable limit. Can Foreigners Own Property Abroad? Freehold, Leasehold and Use Rights covers the wider ownership framework this succession question sits inside.
Before you commit
NA Plot vs Agricultural Land: Which Should You Actually Buy? is relevant where the inherited property is agricultural, given the resale restriction described above. How to Verify a Developer's Track Record and 10 Questions to Ask Before Signing Anything are worth reading before any subsequent sale of an inherited property closes, and Due Diligence When Buying Property in Another Country covers the wider discipline an NRI heir should apply even to a property they already own outright. The Maharashtra Land Revenue Code: A Buyer's Guide and How to Read a 7/12 Extract Before You Buy are relevant for confirming the mutation actually went through correctly in states using that record system. Escaping the City: The Second-Home Mindset is worth reading for an heir weighing whether to keep an inherited property as a second home rather than sell it.
Whatever the state the property sits in, Karjat, Coorg and Igatpuri each fall under India's standard succession framework described above, with no state-specific exception to the personal law that applies.
Sources
- FEMA rules on NRI inheritance, repatriation caps and the NRE/FCNR exception to the USD 1 million limit
- Mutation process and documentation required for NRI intestate succession
Ready to find your next holiday home?
Browse our curated collection of vacation homes and managed farmland across India and beyond.