Liberalised Remittance Scheme: How Much You Can Send Abroad
USD 250,000 a year sounds like a hard ceiling until a buyer actually tries to structure a property purchase against it, at which point the real question turns out to be less about the number itself and more about how many people, transactions and years that number can be spread across. Understanding what actually counts toward the limit, and what does not, matters more than knowing the headline figure.
What the limit actually is, and how it resets
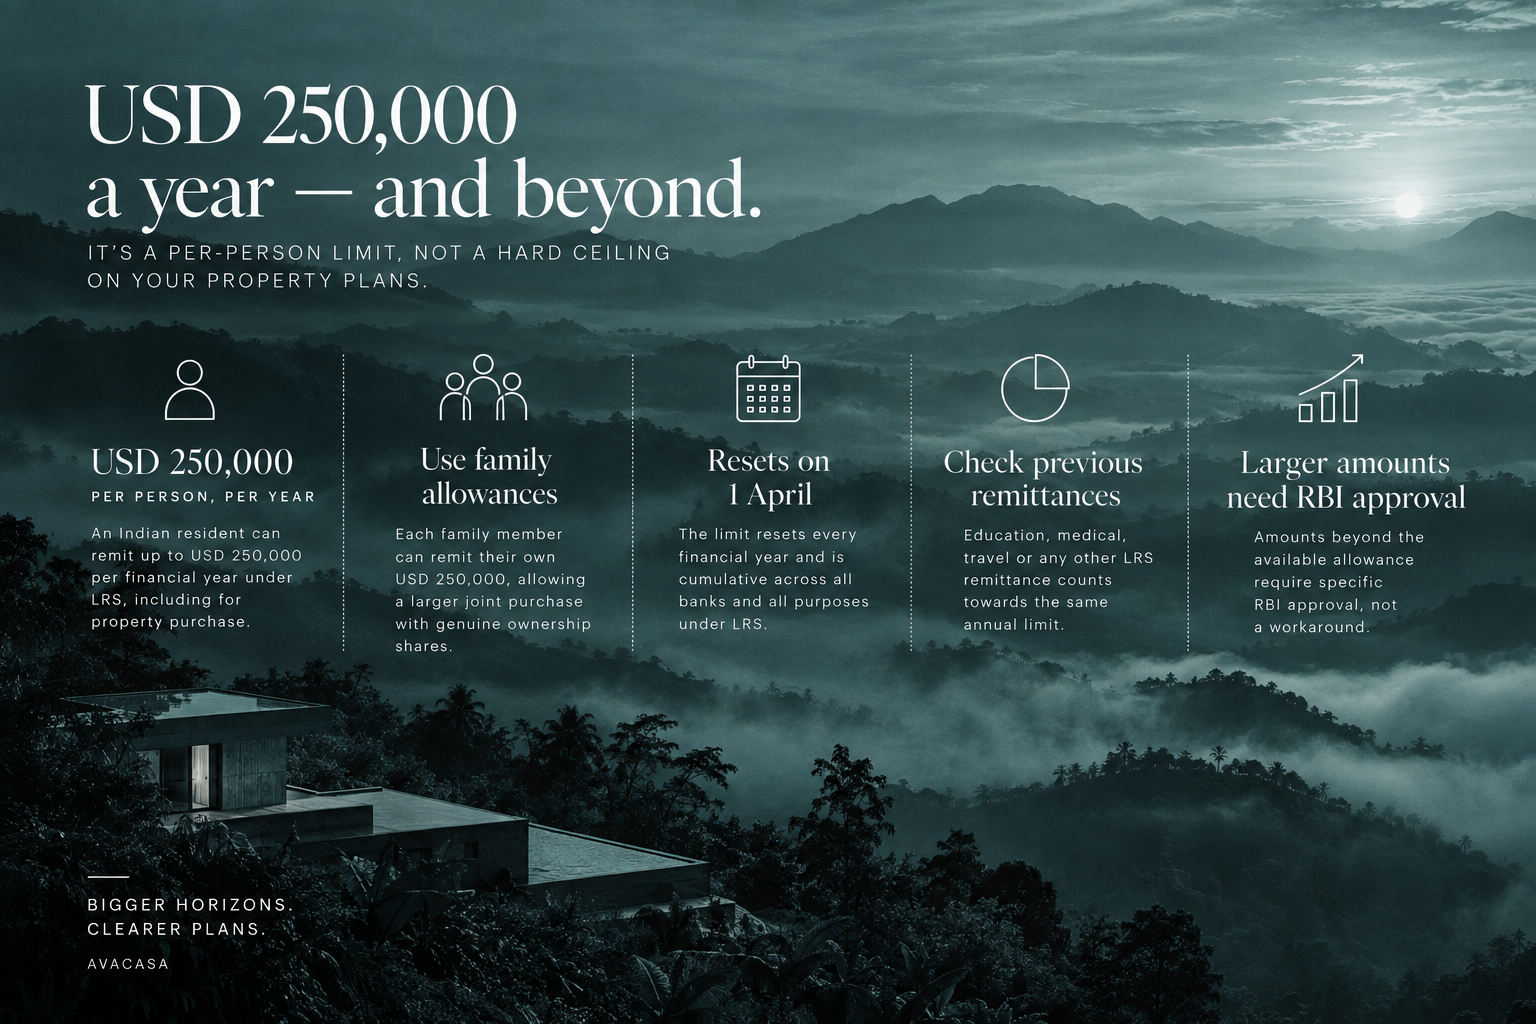
Under the Liberalised Remittance Scheme, a resident Indian individual, including a minor with remittances facilitated by a parent or guardian, can remit up to USD 250,000 per financial year for permitted purposes, which include education, medical treatment, travel, gifts, general investment and property purchase specifically, filed under purpose code S0005 for Indian investment abroad in real estate. This limit resets every financial year on 1 April, and it applies cumulatively across every authorised dealer bank a remitter uses, not separately per bank, which means a buyer cannot extend the effective limit simply by splitting remittances across multiple banks.
The limit is per person, not per property or per transaction
The USD 250,000 cap applies to each individual resident, and a married couple, or any group of family members, can each remit their own separate USD 250,000 in the same financial year, meaning a joint property purchase can draw on a combined limit well above what any single individual could remit alone, provided each remitter genuinely holds a corresponding ownership share reflecting their contribution. This is the detail that changes the practical arithmetic of financing an overseas purchase considerably: a family of four, each remitting their own allowance, has access to a combined USD 1 million in a single financial year without requiring any special RBI approval, provided the ownership structure genuinely reflects each person's actual contribution rather than functioning as a nominal arrangement to circumvent the individual cap.
What counts toward the limit and what does not
Every remittance made under LRS for any permitted purpose in a given financial year counts toward the same cumulative USD 250,000 ceiling, which means a buyer who has already remitted funds earlier in the same financial year for a child's overseas education, a medical expense, or travel has correspondingly less headroom left for a property purchase before the year resets. A buyer planning a large property remittance should check what, if anything, has already been remitted under LRS earlier in the same financial year before assuming the full USD 250,000 is available.
Spreading a purchase across financial years
Where a single individual's allowance genuinely is not sufficient, and a joint purchase structure with family members is not appropriate or available, a buyer can spread a larger purchase across the boundary of two financial years, remitting part of the total in March and the remainder from April onward once the new year's allowance becomes available. This requires the underlying purchase agreement and payment schedule to actually accommodate that timing, which is worth confirming with the seller or developer before assuming the remittance timing can simply be adjusted to fit the LRS calendar.
Exceeding the limit requires specific RBI approval, not a workaround
A remittance need beyond the combined available allowance requires specific RBI approval sought in advance, a genuinely more involved process than the routine LRS remittance most buyers use, and it should not be assumed as a fallback that can be arranged quickly if a purchase price turns out to exceed what the standard allowance covers. TCS also applies on top of the LRS framework itself. TCS on Foreign Remittances: Rates, Thresholds and Credits covers that separate compliance layer in detail.
Why the ownership structure has to genuinely match the contribution
When multiple family members each remit their own LRS allowance toward a single joint purchase, the resulting ownership share on the property's title should genuinely reflect each person's actual financial contribution, both as a matter of good practice and because a mismatch, one person contributing the bulk of the funds while another holds the larger nominal share purely to route more money through their own allowance, is the kind of structuring that regulatory scrutiny specifically exists to catch. A buyer relying on family remittances to reach a purchase price beyond any single individual's cap should document each person's actual contribution carefully and reflect it accurately in the ownership structure from the outset, rather than treating the allocation as a formality to be sorted out informally later.
The bank's own compliance role in this process
Authorised dealer banks processing an LRS remittance are themselves required to verify the purpose and confirm the remitter has not already exceeded their annual limit across other transactions, which means a buyer cannot simply assume a bank will process a remittance without scrutiny purely because it falls under the standard limit on its face. A buyer working with a bank unfamiliar with property-purpose LRS remittances specifically should confirm the bank's own process and documentation requirements well in advance of when the funds actually need to move, since a bank's internal compliance delay at the point of remittance can hold up a purchase timeline just as much as any restriction on the buyer's own side.
What Avacasa recommends
Calculate the actual combined LRS allowance available across every family member genuinely contributing to a joint purchase, rather than assuming a single individual's USD 250,000 is the hard ceiling on the transaction. Check what has already been remitted earlier in the same financial year before finalising a remittance plan, and build any cross-financial-year remittance timing into the purchase agreement itself rather than assuming it can be adjusted after signing.
Before you commit
Can Foreigners Own Property Abroad? Freehold, Leasehold and Use Rights covers the ownership structures this remittance limit sits underneath, and Due Diligence When Buying Property in Another Country covers the wider verification discipline before any offshore purchase. Australians Buying Abroad: CGT and Foreign Income Reporting and UK, Singapore and Gulf Residents: Reporting and Financing cover the equivalent home-jurisdiction pictures for other outbound buyer profiles. How to Verify a Developer's Track Record, How to Negotiate Land Price Like a Pro and 10 Questions to Ask Before Signing Anything round out the practical checklist regardless of the destination.
Whatever the destination, Thailand, Indonesia and Sri Lanka each carry their own local purchase rules, and the LRS remittance limit described above applies at the Indian end before the funds reach any of them.
Sources
- The USD 250,000 per financial year LRS limit, its cumulative application across banks, and the S0005 purpose code for overseas real estate investment
- LRS eligibility for individual residents including minors, and the requirement for specific RBI approval above the standard limit
Ready to find your next holiday home?
Browse our curated collection of vacation homes and managed farmland across India and beyond.