Funding Your Purchase: Legal Channels to Send Money Home
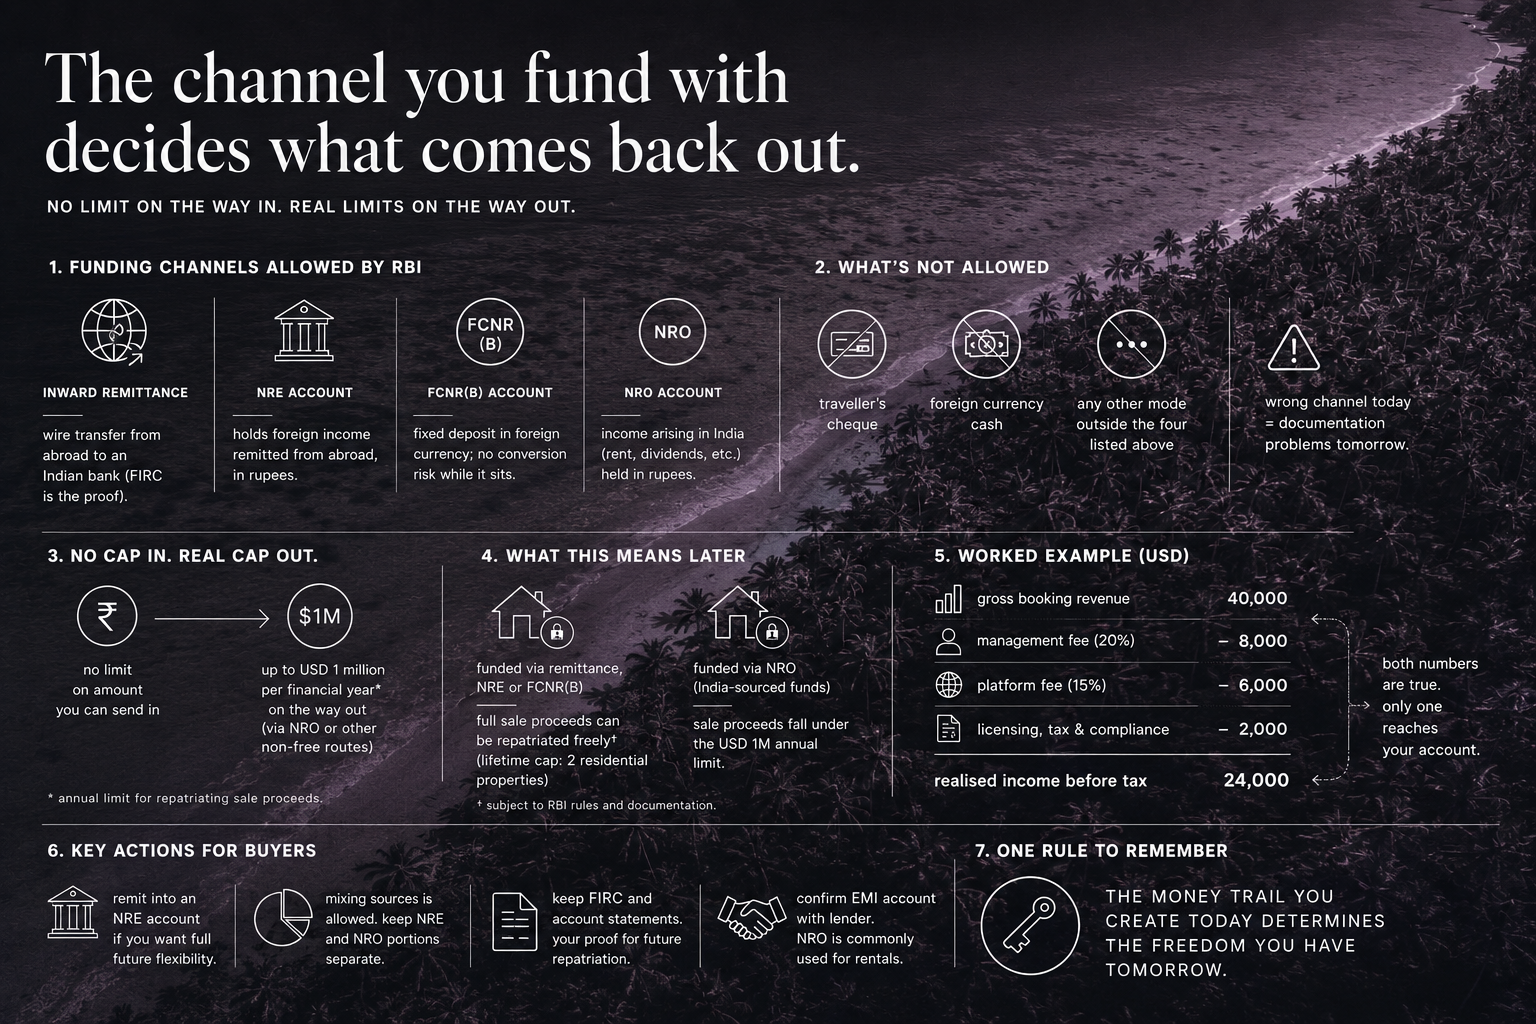
Most Non-Resident Indian (NRI) buyers already know about the USD 1 million cap on taking money out of India. Fewer realise it only runs one way. There is no ceiling on how much you can send in to fund a purchase, only on how much of it, or of what the property later sells for, can leave again. What decides your future flexibility is not the amount you send but the channel you send it through, and that choice gets made the day you fund the purchase, not the day you try to sell.
The channels the law actually allows
The Reserve Bank of India's rules on acquiring property set out exactly which routes count as legitimate payment for an NRI or a Person of Indian Origin (PIO) buying immovable property in India: funds received through normal banking channels by way of inward remittance from abroad, or by debit to a Non-Resident External (NRE) account, a Foreign Currency Non-Resident (FCNR(B)) account, or a Non-Resident Ordinary (NRO) account. That is the complete list.
An inward remittance is simply a wire transfer from your account abroad into an Indian bank, and the bank issues a Foreign Inward Remittance Certificate (FIRC) for it, which is the single most important document to keep from the entire transaction. It records the sending bank, the amount, the currency it left in, and the date, and it is the evidence a bank will ask for years later if you want to establish that a given sum genuinely originated abroad rather than inside India. An NRE account holds foreign income you have remitted to India, held in rupees but funded from abroad. An FCNR(B) account holds a fixed deposit in foreign currency itself rather than rupees, so it carries no currency conversion risk while the deposit sits there, only when it is eventually drawn down. An NRO account holds income that already arises inside India, such as rent from a property you already own, or dividends from Indian investments.
Say a buyer is funding a farmhouse purchase in Karjat priced at 1,60,00,000 rupees. Wiring the full amount from a foreign bank account into a fresh NRE account, drawing an FIRC for that single transfer, and paying the seller from that account creates one clean document trail: one remittance, one certificate, one source. Splitting the same purchase across three transfers into an existing NRO account that also receives rent from an unrelated flat in Pune creates a mixed pool where a bank, or an heir, has to work out years later which rupees came from abroad and which arose in India, a distinction that by then depends entirely on records rather than memory.
What is not allowed
The same rule that lists what is permitted is explicit about what is not: payment cannot be made by traveller's cheque, by foreign currency notes physically carried into the country, or by any other mode outside the four listed above. Cash beyond the ordinary limits that apply to any property transaction in India is not a route around this either. A single payment routed the wrong way does not usually stop the sale from closing, but it does create a documentation gap that surfaces later, typically when you or your heirs try to repatriate proceeds and cannot show where the original money came from.
No cap on the way in, a real one on the way out
This is the point sellers of "compliance checklists" most often blur, because it makes FEMA sound more restrictive than it is on the funding side. Sending money into India to buy property has no upper limit under the Reserve Bank's rules, whether it lands in an NRE, NRO or FCNR(B) account. A buyer funding a large purchase in one transfer is not doing anything irregular by virtue of the amount alone.
The USD 1 million per financial year figure that most NRI buyers have heard of applies to the other direction entirely: repatriating sale proceeds once a property already owned in India is sold, and even then only for proceeds routed through an NRO account or otherwise not already eligible for freer treatment. Selling Indian Property as an NRI: The End-to-End Process covers that side of the transaction in full. The two are easy to conflate and describe opposite situations: funding a purchase, and later exiting one.
The channel you choose now decides what you can take out later
This is the part that actually matters for a buyer, because it is decided at the point of funding, not negotiable afterward. Property bought using funds remitted from abroad, held in an NRE account, or paid from an FCNR(B) deposit, can later have its full sale proceeds repatriated without being pulled into the USD 1 million annual limit, subject to a lifetime cap of two such residential properties. Property funded through an NRO account, because the underlying money already originated in India, does not carry that same freer status: when you eventually sell, those proceeds fall under the general repatriation limit rather than outside it.
In practice this means a buyer moving foreign savings into India specifically to purchase should route them as an inward remittance into an NRE account rather than parking them in an NRO account first and paying from there, if keeping the exit as unrestricted as possible matters to you. Once the money has been converted to rupees inside an NRO account, its origin as foreign-earned funds becomes harder to establish years later, whatever the reality was at the time.
Financing with a home loan
An Indian bank or housing finance company can lend to an NRI buyer directly. Lenders vary on the specifics, but financing commonly runs in the 75 to 85% range of the property's value, and tenures are typically shorter than what a resident borrower gets, often capped well short of the 30-year terms available domestically. Confirm both figures with the specific lender rather than assuming either number. The loan itself does not change the funding rules above: the booking amount, the down payment and every subsequent EMI must still be routed through an NRE or NRO account rather than paid directly from a foreign bank account to the Indian lender. NRO is commonly used here specifically because rental income from the property being financed, which is India-sourced, can be applied directly to the EMI without an extra conversion step, but the same later-repatriation trade-off described above still applies to that portion of the funding.
Funding a purchase from more than one source
Few buyers fund a property from a single clean transfer in practice. A common pattern is a large remittance from abroad covering most of the price, topped up with existing NRO balances built up from Indian rental income or maturing fixed deposits. Both are permitted, and there is no rule against combining them on one purchase. What changes is that the resulting property is no longer uniformly one kind of asset for repatriation purposes: the portion traceable to the foreign remittance carries the freer NRE-style treatment, and the portion traceable to the NRO balance carries the general limit, in roughly the proportion each contributed. Keeping the FIRC for the remittance and a clear statement showing the NRO portion separately is what lets that proportion actually be reconstructed later, rather than argued about.
A jointly owned purchase with a resident Indian family member follows the same funding rules on the NRI buyer's side; the resident co-owner's contribution is not restricted by FEMA at all, since these rules govern the non-resident party's payment, not the transaction as a whole.
What this means for a purchase in practice
Decide the funding channel before the first payment is made, not after, since it is not something a lawyer can fix retroactively at the point of sale. Four steps make the difference:
- If keeping full future repatriation open matters, remit directly into an NRE account rather than routing funds through an NRO account first, even briefly.
- If part of the funding is India-sourced income already sitting in an NRO account, using it is fine, but go in knowing that portion inherits the general repatriation limit, and keep it identifiable as a separate contribution rather than merged with other funds.
- Keep the FIRC for every remittance and the account statements showing the funds moving from account to purchase. This is the evidence a bank asks for when you eventually want to move money back out, and it is far easier to produce at the time than to reconstruct years later, especially if you are not the one handling the eventual sale.
- If a loan is involved, confirm with the specific lender which account the EMIs will draw from before signing, rather than assuming it will be whichever account is more convenient at the time.
None of this changes who can buy or what: Who counts as an NRI, OCI or PIO for property purposes and Can NRIs Buy NA Plots in India? Rules, FEMA & Repatriation cover eligibility and property type. The NRI Documentation Checklist for Buying Land lists what your lawyer will want alongside the funding paperwork, and if the purchase will be completed without you physically present, Power of Attorney for Overseas Buyers, Done Safely covers the other piece of that remote transaction. Agricultural land carries its own separate restriction regardless of how the purchase is funded; Why NRIs Can't Buy Agricultural Land - and the Workarounds explains where that line sits. If the state you are buying in is Maharashtra, The Maharashtra Land Revenue Code: A Buyer's Guide covers what else the purchase depends on once the money has arrived, and Capital Gains Tax on Selling Land in India: The Complete Guide picks up the calculation on the other side of a future sale.
For where this actually plays out, the Karjat, Alibaug and Goa destination guides show the range of purchases these funding rules apply to in practice.
Sources
- Reserve Bank of India, Master Direction on Acquisition and Transfer of Immovable Property in India: permitted modes of payment for NRI and PIO purchasers, and prohibited modes
- Foreign Exchange Management (Non-Debt Instruments) Rules, 2019
Ready to find your next holiday home?
Browse our curated collection of vacation homes and managed farmland across India and beyond.