Capital Gains Tax on Selling Land in India: The Complete Guide
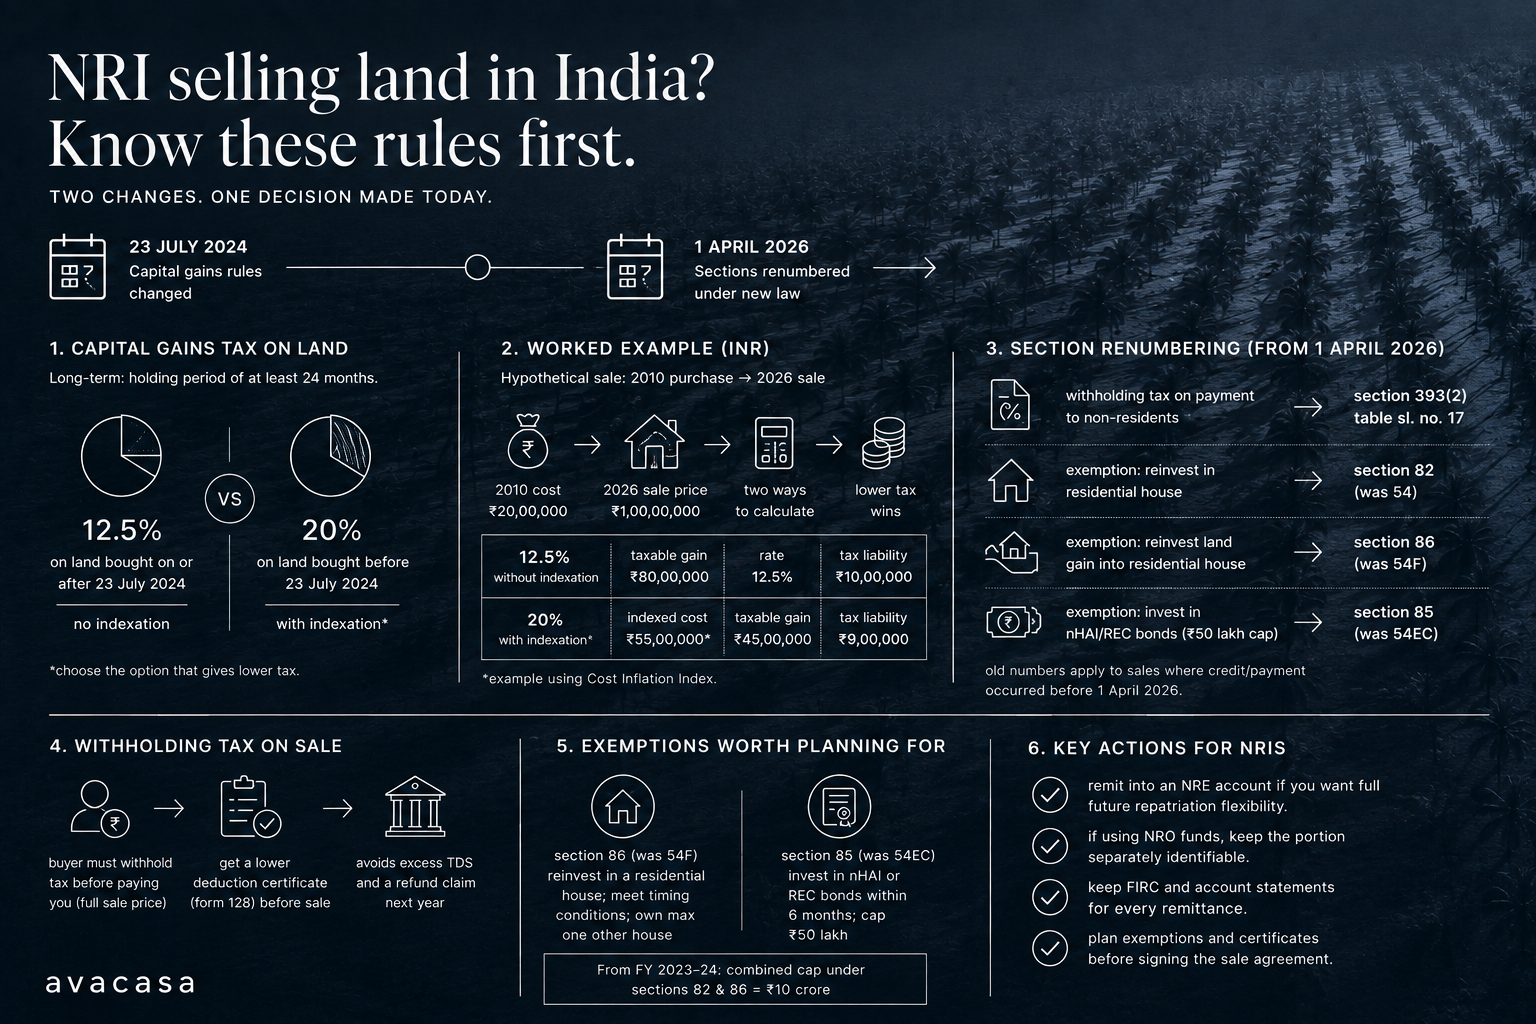
An NRI selling inherited or long-held land in India this year is dealing with two changes at once, not one. The Finance (No. 2) Act, 2024 rewrote the capital gains rules from 23 July 2024, and the Income Tax Act, 2025 then renumbered almost every section those rules live in, effective 1 April 2026. A seller working from an article written even a year ago is very likely reading both the wrong rate and the wrong section number.
What changed, and when
For land and buildings bought on or after 23 July 2024, long-term capital gains are taxed at a flat 12.5%, with indexation, the adjustment that inflated the purchase cost to reduce taxable gain, removed entirely. For land bought before that date, a transitional rule applies: the seller can choose between 12.5% without indexation or 20% with indexation, and pick whichever produces the lower tax bill. This choice is not automatic and has to be calculated both ways before filing, since which option wins depends entirely on how much the land has appreciated relative to inflation over the holding period. Long-term status itself requires a holding period of at least 24 months for land and buildings.
Working the transitional choice with real arithmetic
Take a hypothetical plot bought in 2010 for 20 lakh rupees, sold in 2026 for 1 crore rupees, numbers chosen only to make the comparison legible rather than a claim about any specific transaction. Under the 12.5%-without-indexation route, the taxable gain is the full difference between sale price and original cost, 80 lakh rupees, taxed at 12.5%, a liability of 10 lakh rupees. Under the 20%-with-indexation route, the original 20 lakh rupee cost is adjusted upward using the Cost Inflation Index to account for inflation over the holding period; if that indexed cost works out to, say, 55 lakh rupees, the taxable gain shrinks to 45 lakh rupees, and at 20% the liability is 9 lakh rupees, marginally lower than the flat-rate route in this specific case. Change the assumptions, a shorter holding period, a smaller Cost Inflation Index adjustment, or a smaller gain relative to the original cost, and the flat 12.5% route often wins instead. There is no shortcut that avoids running both calculations for a specific sale; the answer depends entirely on how much of the price appreciation was real gain versus how much was simply inflation over the years the land was held.
The renumbering that follows on 1 April 2026
The Income Tax Act, 2025 replaced the 1961 Act from 1 April 2026, and the sections an NRI seller has spent years hearing about now sit under different numbers, though the substantive rules are unchanged. Section 195, the withholding tax provision on payments to non-residents, is now Section 393(2), Table Serial No. 17. Section 54, the exemption for reinvesting gains into a residential house, is now Section 82. Section 54F, the exemption for reinvesting gains from a non-house asset such as land into a residential house, is now Section 86. Section 54EC, the exemption for investing gains into specified NHAI or REC bonds, is now Section 85. Any transaction where credit or payment occurs on or after 1 April 2026 falls under the new numbering; a sale that closed before that date is still governed by the 1961 Act's original section numbers.
What this means for an NRI seller specifically
The buyer of an NRI's land is required to withhold tax at source before paying the seller, under what is now Section 393(2) Sl. No. 17, and this withholding is calculated on the full sale consideration, not on the actual capital gain, unless the seller has first obtained a lower deduction certificate from the assessing officer. Since the withheld amount is almost always larger than the seller's real tax liability, most NRI sellers who skip the certificate end up filing for a refund the following year rather than receiving the correct amount at the time of sale. Applying for the certificate, using what was Form 13 and is now Form 128, before the sale closes is the single step that avoids that gap, and it needs to be done ahead of the transaction, not after money has already changed hands. Selling Indian Property as an NRI: The End-to-End Process covers the full transaction sequence this withholding step sits inside.
The exemptions worth planning around before the sale, not after
Section 86, formerly Section 54F, lets an NRI reinvest the gain from selling land into a residential house and avoid tax on that gain, subject to conditions on timing and on not owning more than one other house at the time. Section 85, formerly Section 54EC, offers a narrower but more flexible route: investing the gain into specified NHAI or REC bonds within six months of the sale, capped at 50 lakh rupees, with no requirement to buy property at all. From FY 2023-24 onward, the combined exemption available under Sections 82 and 86 is capped at 10 crore rupees; a gain above that ceiling is only partially shielded, with the excess taxed at the standard rate regardless of how it is reinvested. Deciding which of these exemptions to use, or whether to use one at all, is a calculation worth doing before the sale is structured, since the reinvestment windows on both routes start running from the sale date rather than from whenever the paperwork gets sorted out.
What Avacasa recommends
Confirm the acquisition date against the 23 July 2024 threshold before assuming which tax rate applies, and run both the 12.5% and 20%-with-indexation calculations if the land was bought before that date, since the lower figure is not always the obvious one. Apply for the lower deduction certificate ahead of any sale rather than after, since the alternative is financing a tax refund claim for a year rather than receiving the correct amount at closing. And treat the reinvestment exemptions under Sections 82, 85 and 86 as a decision to make before the sale agreement is signed, not a form to fill in afterward. Funding Your Purchase: Legal Channels to Send Money Home is relevant for an NRI planning to repatriate sale proceeds once the tax position is settled, and Currency Risk When Buying and Holding Property Abroad is worth reading for the same reason, since converting rupee sale proceeds back to a foreign home currency carries its own separate cost.
Effective dates and sources
The Finance (No. 2) Act, 2024 changes to capital gains rates, indexation and holding periods took effect 23 July 2024. The Income Tax Act, 2025, including the section renumbering described above, took effect 1 April 2026 and applies to transactions where credit or payment occurs on or after that date.
The Maharashtra Land Revenue Code: A Buyer's Guide is worth reading alongside this for anyone selling agricultural or NA-classified land specifically, since state-level land classification rules operate independently of the central capital gains regime covered here. Due Diligence When Buying Property in Another Country and Financing a Property Purchase Abroad are relevant for an NRI using sale proceeds from Indian land to fund a purchase elsewhere, and Residency and Visa Routes Tied to Property Ownership covers a related question for the same buyer profile. Can Foreigners Own Property Abroad? Freehold, Leasehold and Use Rights rounds out the picture for an NRI seller thinking about where the proceeds go next.
Whatever the destination for reinvestment, Goa, Karjat and Dubai are worth a look for an NRI seller weighing where sale proceeds from Indian land go next.
Sources
- Finance (No. 2) Act, 2024: capital gains rate and indexation changes effective 23 July 2024
- Section 195 renumbered to Section 393(2), Table Serial No. 17, under the Income Tax Act 2025, effective 1 April 2026
- Sections 54, 54F and 54EC renumbered to 82, 86 and 85 respectively under the Income Tax Act 2025
- The Rs 10 crore combined cap on Section 54/54F-equivalent exemptions, effective FY 2023-24
Ready to find your next holiday home?
Browse our curated collection of vacation homes and managed farmland across India and beyond.