Double Taxation Relief on Indian Property Income
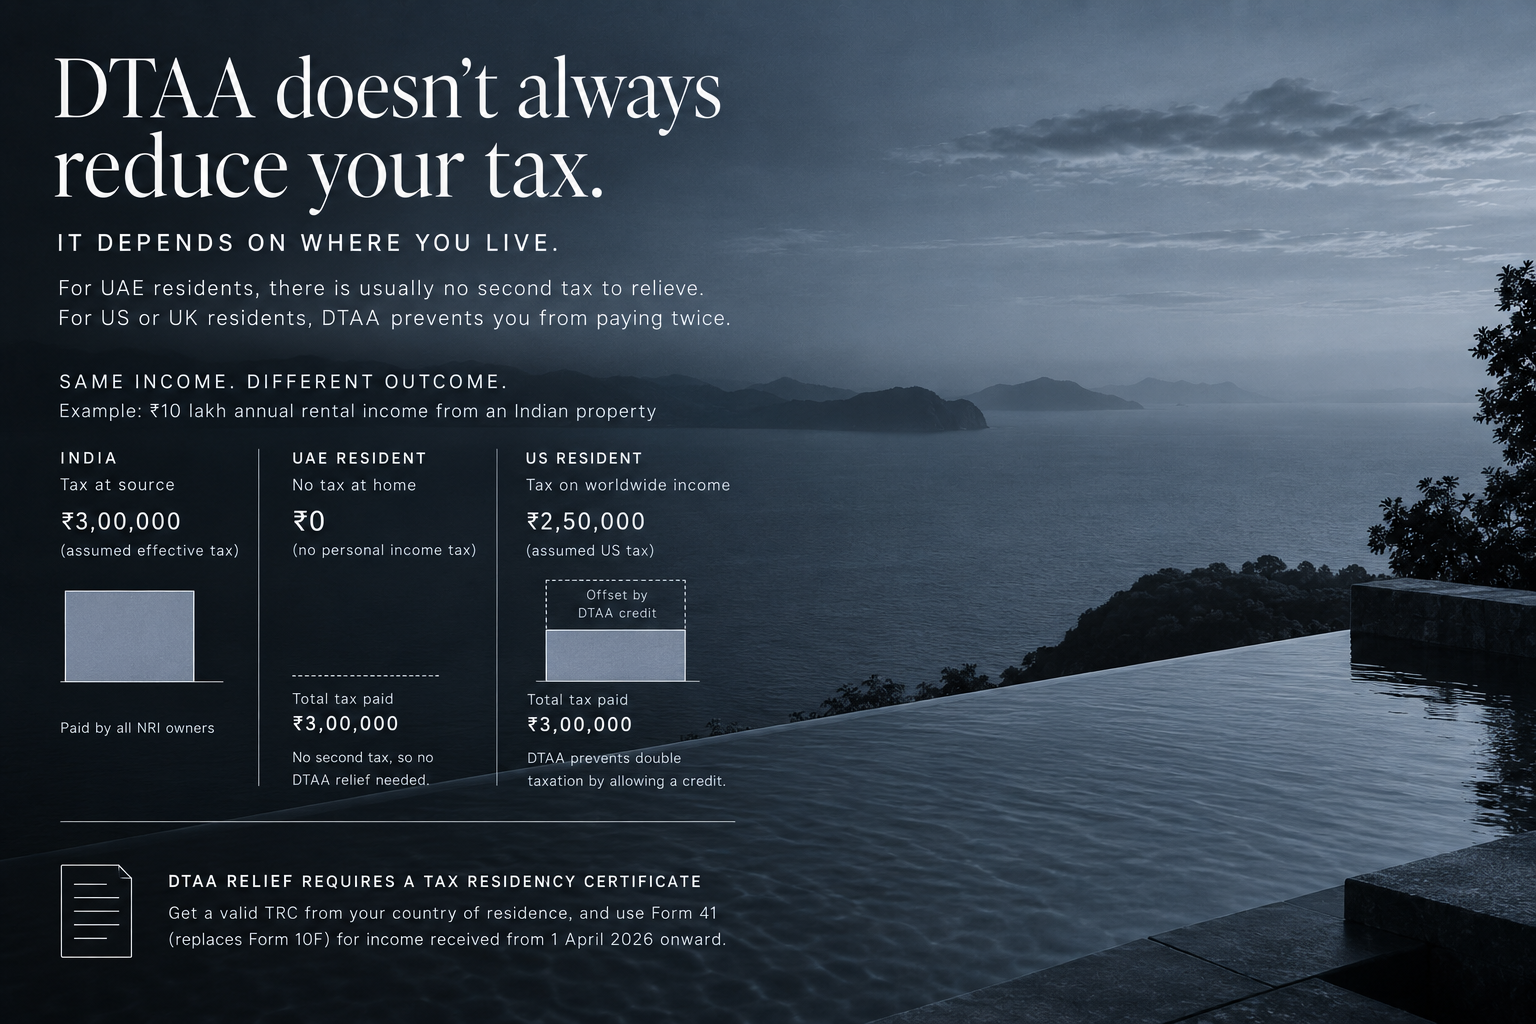
"DTAA protects you from double taxation" is true, and it is also the sentence most likely to leave an NRI property owner with the wrong expectation. What the treaty actually does depends entirely on how the owner's country of residence taxes income in the first place, and for the single largest group of NRI property owners, those resident in the UAE, the treaty has almost nothing to relieve, because there was never a second tax to begin with.
What DTAA actually does, and what it does not
India holds double taxation avoidance agreements with more than 90 countries, including the UAE, the UK, the US, Singapore and Canada, and the mechanism is straightforward in principle: income taxed once in India should not be taxed again in full by the country where the owner actually lives. In practice, the treaty achieves this in one of two ways depending on the specific article involved. Rental income and capital gains from Indian immovable property are taxed in India as the source country, that much is consistent across every one of these treaties. What differs is what happens next, once that Indian tax has been paid, in the owner's country of residence.
Why the UAE case is different from the US or UK case, and why that matters
A US-resident or UK-resident NRI owes tax on worldwide income in their country of residence, India-sourced rental income included, and without DTAA relief that income would be taxed twice: once in India as the source country, and again at home. The treaty's credit method is what actually prevents that, allowing the tax already paid in India to offset the liability calculated at home, so the owner pays the difference rather than the full amount twice. This is where DTAA delivers a genuine, calculable saving.
A UAE-resident NRI is in a structurally different position, because the UAE does not levy personal income tax on rental income or capital gains at all. There is no second tax at home for the treaty to relieve, because the second tax never existed in the first place. For this group, the meaningful benefit is not really "avoiding double taxation" in the sense the phrase implies, it is confirming that Indian withholding itself is correctly calculated and not overstated, since there is no home-country liability to credit it against. A UAE-resident NRI expecting the treaty to reduce an Indian tax bill directly, the way it does for a US or UK resident, is applying the wrong mental model to their own situation.
A worked comparison, with the numbers shown
Take a hypothetical NRI earning 10 lakh rupees in annual rental income from an Indian property, numbers chosen only to make the comparison legible rather than a claim about any specific owner. India withholds tax on that income at source; assume, for illustration, an effective Indian tax of 3 lakh rupees on it. A US-resident NRI now has to report that same 10 lakh rupees as part of their worldwide income on their US return, where it might attract a notional US tax liability of, say, 2.5 lakh rupees equivalent. Without DTAA, the US-resident owner would owe the full 2.5 lakh again, on top of the 3 lakh already paid in India, a combined 5.5 lakh on 10 lakh of income. With the treaty's credit method, the 3 lakh already paid in India offsets the US liability, and since the Indian tax already exceeds the calculated US liability in this example, no further US tax is actually owed, only the original 3 lakh paid once. A UAE-resident NRI earning the identical 10 lakh rupees simply pays the 3 lakh in India and stops there, not because of anything the treaty specifically does, but because the UAE was never going to tax that income again regardless of what the treaty said. The arithmetic looks identical at the end for both owners in this example, but only one of them needed the treaty to get there.
The certificate that makes any of this actually work
None of this relief is automatic. Section 90(4) requires a valid Tax Residency Certificate from the owner's country of residence before a DTAA benefit can be claimed at all, and where the TRC does not carry every detail the Indian tax authorities require, a supplementary declaration has to be filed alongside it. Processing time for the TRC itself varies meaningfully by country and is worth planning around rather than discovering under time pressure: the UAE's Federal Tax Authority typically issues one within roughly a week, Singapore's authority is similarly fast, the UK's process runs closer to two to three weeks, and the US IRS process is the outlier, commonly taking six to twelve weeks from application to certificate. An NRI planning a sale or a large rental-income filing around a specific date needs to start the TRC application well ahead of that date, particularly for the US, where the processing time alone can span an entire quarter.
The declaration form just changed, on top of everything else
The supplementary declaration that accompanies an incomplete TRC has, until now, been Form 10F. Under the Income Tax Act, 2025, Form 10F is replaced by Form 41, a self-declaration under Section 159(8) of the new Act, mandatorily filed online with no offline or physical alternative accepted. Form 41 applies to income received from 1 April 2026 onward; income received in the 2025-26 financial year, ending 31 March 2026, still falls under the old Act and Form 10F. An NRI whose rental income straddles that date is filing under two different regimes for the same property in the same year, which is worth flagging to whoever prepares the return rather than assuming one form covers the full year.
What Avacasa recommends
Confirm which category actually applies before assuming DTAA delivers a direct tax saving: a genuine credit-method benefit for residents of countries that tax worldwide income, or, for UAE residents specifically, a question of correct withholding rather than double-taxation relief in the conventional sense. Start the Tax Residency Certificate application well ahead of any planned sale or major rental filing, budgeting for the US timeline in particular, and confirm whether Form 10F or Form 41 is the correct declaration for the specific income period in question. TDS on Property Purchase: When and How Much and Lower TDS Certificate: Form 13 for NRI Sellers cover the withholding mechanics this treaty relief sits alongside, and getting the TRC and the withholding certificate aligned is what actually determines how much cash reaches the owner at the time of a transaction rather than a year later.
Effective dates and sources
DTAA relief on Indian property income operates under whichever specific treaty applies to the owner's country of residence, with capital gains and rental income from Indian immovable property taxed in India as the source country under every treaty examined here. Form 41 replaces Form 10F for income received from 1 April 2026 onward under the Income Tax Act, 2025; income from the 2025-26 financial year remains governed by the 1961 Act and Form 10F.
Capital Gains Tax on Selling Land in India: The Complete Guide covers the underlying Indian tax calculation this treaty relief applies against, and Selling Indian Property as an NRI: The End-to-End Process covers where TRC timing fits inside a full sale sequence. Funding Your Purchase: Legal Channels to Send Money Home and Currency Risk When Buying and Holding Property Abroad are relevant for an NRI repatriating rental income or sale proceeds once the tax position across both countries is settled, and Residency and Visa Routes Tied to Property Ownership covers a related cross-border question for the same buyer profile. Can Foreigners Own Property Abroad? Freehold, Leasehold and Use Rights is worth reading for an NRI weighing a purchase abroad against the Indian tax position covered here.
Whatever the property, Goa, Karjat and Mulshi are common destinations for the NRI buyers this treaty relief actually applies to.
Sources
- India's DTAA network of 90+ countries, and the source-based taxation of immovable property gains under the residence article
- Tax Residency Certificate requirement under Section 90(4) and processing times by country
- Form 10F replaced by Form 41 under Section 159(8) of the Income Tax Act 2025, effective for income from 1 April 2026
Ready to find your next holiday home?
Browse our curated collection of vacation homes and managed farmland across India and beyond.